

DailyPay On-Demand Pay
DailyPay Inc
- 4.7
- 16.68K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
DailyPay On-Demand Pay Pros and Cons
Pros
- Instant access to earned wages.
- Supports various payment methods.
- User-friendly interface.
- Secure transactions.
- Reliable customer support.
Cons
- Limited to partnered employers.
- Fees may apply for transfers.
- Requires internet connection.
- Not available globally.
- Account setup can be tedious.
 Analysis by All-app
I tend to think of DailyPay On-Demand Pay less as a spare paycheck and more as a tool for smoothing out the awkward gaps between work and bills. That distinction matters in a household: one person may need to deal with a time-sensitive expense, while rent, groceries, and other shared costs still have to fit the usual budget. Used thoughtfully, early access to earned wages can help with timing; it does not create extra income or make a recurring shortfall disappear.
When one person’s cash-flow crunch affects everyone
Picture a shared household where a utility bill is due before payday and the person responsible for paying it has already earned wages that have not reached their normal pay date. DailyPay may offer a way to address that timing problem, provided their employer makes the service available and their account shows funds they can access. The practical benefit is not simply “money sooner”; it is being able to make a decision before a late bill or a missed payment complicates the week.
I would still treat an early transfer as a change to the timing of the next paycheck, not as a bonus. If one household member uses available earnings to cover a shared expense, it helps to agree whether that amount counts toward their usual contribution or whether someone else will reimburse them. That small conversation can prevent an app-based convenience from turning into confusion between partners, roommates, or relatives.
Keep access personal, even when expenses are shared
For a shared-device household, I would keep the financial account tied to the person whose wages are involved. The app concerns individual pay, so letting someone else browse or initiate actions from an unlocked phone can blur an important boundary. A safer routine is to use the account holder’s own device and sign-in, and to avoid leaving the app open when handing a phone to a child, partner, or roommate.
Shared bills do not require shared credentials. A household can coordinate the amount needed and the date it is due without giving every person access to another person’s wage information. Before setting anything up, the worker should check that their employer participates and follow the employer-specific process shown in the app. If the household depends on another member’s income instead, that person needs to make their own decision about whether early access fits their pay cycle.
Coordination that does not replace budgeting
A useful approach is to check the expense first, then decide whether using earned wages is preferable to the household’s ordinary alternatives. For a bill with a known due date, compare the cost and timing of an early transfer with asking the provider about a later payment date or using money already set aside. DailyPay can be useful when the timing is genuinely tight, but it is worth avoiding a habit of drawing down available pay for everyday purchases that could wait.
One non-obvious trade-off is that solving this week’s problem may leave less in the next scheduled paycheck. I would note the amount moved and adjust the household’s next few days of spending accordingly, rather than treating the remaining pay as if nothing changed. If more than one person contributes to shared costs, a quick check-in before a transfer can keep groceries, rent, and other commitments from being counted twice or overlooked.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Who may prefer another option
This is most appealing to a worker whose employer supports DailyPay and who occasionally faces a mismatch between earned income and bill dates. It is less suitable for someone who needs a new source of income, expects access regardless of employer participation, or is trying to solve a persistent gap between monthly earnings and expenses. In those cases, a budget review, a conversation with a bill provider, or a different form of assistance may address the underlying issue more directly.
Compared with waiting for the regular payroll deposit, on-demand pay offers more flexibility over timing, but that flexibility asks the user to manage the effect on the next payday. Compared with borrowing, it is tied to wages already earned rather than being a separate loan, though that does not make every transfer cost-free or automatically the best choice. I would check the terms displayed for my own account before choosing a transfer method, and compare any charge with the cost of simply waiting.
Age, trust, and a realistic household boundary
The app is rated for Everyone, but its purpose is financial and its usefulness depends on having eligible employment and an employer that offers access. That age label should not be confused with a reason for a child to manage an adult’s pay account. If a younger family member uses the same phone for games or messages, I would close the finance app and keep account access private; household convenience is no reason to share a sign-in.
Trust also means being clear about what the app can and cannot do for the household. It can help an eligible worker reach some earned wages before the normal payday, but it cannot guarantee that a particular expense will be covered or remove the need to plan for upcoming bills. I would verify the available amount and transfer terms in the account before promising a roommate or family member that money will arrive by a specific time.
Getting Paid Whenever You Need
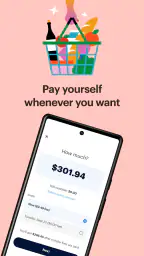
Imagine this: it's Wednesday, and you've got an unexpected bill to pay. Normally, you'd have to wait until Friday to get your paycheck. But with DailyPay On-Demand Pay, you can access your earned wages anytime you need them. It's like having a financial safety net that you can tap into whenever life throws you a curveball.
Easy Setup and Integration
The setup process is a breeze. Once you've downloaded the app, linking it to your employer's payroll system is straightforward. The app integrates seamlessly, so you don't have to worry about complex procedures or red tape. It's designed to make your life easier, not add more stress.
In practice, I would start by confirming employer eligibility before planning around the service. Early wage access depends on a connection to the employer’s payroll process, so it is not a universal substitute for a bank account or a benefit available to every worker. If the app cannot connect as expected, I would check the employer’s instructions rather than repeatedly changing account details or assuming that a transfer is already on its way.
User-Friendly Interface
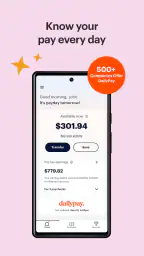
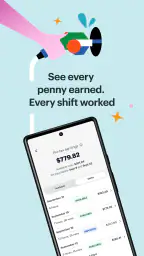
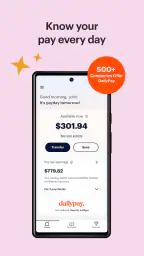
One of the first things I noticed about the app is its user-friendly interface. Everything is laid out clearly, making navigation a piece of cake. Whether you’re checking your available balance or transferring funds to your bank account, everything is just a few taps away. It's as if the app developers knew exactly what we needed and delivered it with simplicity in mind.
That kind of quick access is most useful when it supports a deliberate choice rather than a reflex. I would check the available balance, identify the exact bill or purchase, and then move only what is needed. This keeps the app’s convenience from encouraging a larger withdrawal simply because the option is visible. It also makes it easier to explain a shared expense without exposing the rest of a personal pay account.
Security You Can Rely On
I know what you're thinking – is it safe? Absolutely. The app uses top-notch security features to ensure your financial data is protected. In a world where digital security is paramount, DailyPay takes this seriously, giving you peace of mind alongside financial flexibility.
For my part, I would pair any app’s security measures with ordinary account habits: keep the phone’s screen lock enabled, do not share sign-in details, and be cautious about leaving a finance app open on a device used by several people. Those steps matter especially when a household shares tablets or phones, because someone else’s convenience should not expose a worker’s wage or transfer choices.
Transparent Fees
Now, you might be wondering about the cost. The app is pretty transparent about its fees. While there is a small fee for transferring your funds instantly, in my opinion, it’s a small price to pay for the convenience it offers. Plus, you can always choose to get your money through standard transfer if you prefer to avoid any extra charges.
I would treat speed as a choice to weigh, not a default setting. If a bill is due immediately, paying for an instant option may be worthwhile; if it can wait, the standard route may make more sense. Before confirming, read the amount and timing shown for that particular transfer. A fee that seems minor once can become less attractive if the same urgency keeps recurring, which is a sign to revisit the household budget or bill schedule.
What to expect before relying on it
DailyPay is a free finance app from DailyPay Inc, with a 4.7 average from around 203,000 ratings and more than 1 million installs. It has been available since December 7, 2018, and version 37.0.0 requires Android 9 or later. Those figures suggest that it is an established option, but popularity does not tell me whether a particular employer participates or whether the available balance will match a specific household need.
A common practical question is whether the app means every worker can access wages whenever they choose. I would not plan on that: the key first step is checking employer availability and then reviewing what the account offers. Another question is whether getting money early changes the next payday. Since the transfer advances earned wages, I would plan for the later paycheck to reflect money already accessed, rather than treating the transfer as extra pay.
People also often want to know whether they must pay to use the app. The app itself is free, while the transfer choice can affect whether a fee applies; I would check the terms presented before confirming instead of assuming every method costs the same. And if a household member needs money for an expense, the account holder should decide and make the transfer themselves. The app is not a household pool, so clear agreement about shared bills remains useful.
Final Thoughts
In a nutshell, DailyPay is like having your own personal payday whenever you need it. It’s a reliable companion for those unexpected moments when you need cash fast. The convenience, coupled with the security and transparency, makes it a go-to app for anyone looking to take control of their finances. So, if you're tired of waiting for payday, give it a try and see how it can change your financial routine. Trust me, you’ll wonder how you ever lived without it!
My more measured recommendation is to consider it a useful option for occasional timing problems, not a replacement for a steady plan or a guarantee of instant money. It is a stronger fit when the employer supports it, the need is specific, and the user has thought through how an early transfer affects the next payday. For households sharing expenses, a private account and a simple conversation about who covers what make the convenience easier to manage.
If you are comfortable checking the transfer terms and keeping your account separate from shared-device use, DailyPay can be worth exploring. If you need predictable access that does not depend on your employer, or if you are trying to cover a continuing shortfall, I would look at other options first. That is the difference between using on-demand pay as a helpful bridge and expecting it to solve a problem it was not built to remove.
Frequently Asked Questions
What is DailyPay and how does it work?
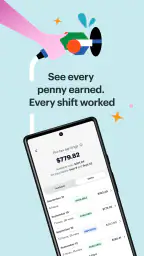
DailyPay is an app that allows employees to access their earned wages before the traditional payday. By connecting with your employer, the app tracks your earnings and lets you transfer a portion of your paycheck to your bank account or debit card whenever needed. This service provides flexibility and helps you manage your finances more efficiently, especially in emergencies.
Is DailyPay secure and safe to use?
Yes, DailyPay is committed to ensuring the security and privacy of its users. The app uses bank-level encryption to protect your personal information and transactions. Additionally, it complies with industry standards and regulations to maintain a safe and secure environment for all users. Always ensure your app is updated to benefit from the latest security features.
Are there any fees associated with using DailyPay?
While signing up for DailyPay is generally free, there may be fees associated with instant transfers. These fees can vary based on your employer’s agreement with DailyPay. Some users may opt for free scheduled transfers, which allow you to receive your funds on the next business day without any charges. Always check the terms and conditions for any potential fees before using the service.
Can I use DailyPay with any employer?
No, DailyPay can only be used if your employer has partnered with DailyPay. The app needs to be integrated with your employer's payroll system to track your earnings accurately. If your employer is not currently offering DailyPay, you might consider suggesting it to them as a potential benefit for employees.
How quickly can I access my earnings with DailyPay?
DailyPay offers flexibility in accessing your earnings. You can choose to transfer your funds instantly for a small fee, or opt for a next-day transfer at no charge. The instant transfer option is particularly useful in emergency situations where you need immediate access to your money. The app ensures you're never left waiting for your hard-earned wages.


